What IDV Means in Car Insurance and Why It Matters at Renewal
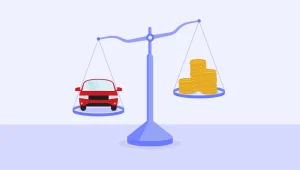
Most car owners compare renewal quotes on premium alone and overlook the IDV figure. That figure, the Insured Declared Value, decides how much you could receive if your car is stolen or written off. Accept an IDV that is too low and the payout may fall well short of what the car is worth. Accept one that is too high and you pay extra premium every year for value the car no longer has.
What IDV Actually Means
IDV is the insurer’s estimate of your car’s current market value. It works as the sum insured for the own-damage part of your policy, which means it is the maximum amount payable if the car is stolen or declared a total loss. It does not include registration charges, road tax or the cost of insurance itself.
When you compare four-wheeler insurance quotes, IDV is one of the few figures that changes both what you pay and what you can recover. Two quotes with similar premiums can carry very different IDVs, so the cheaper one is not always the better deal.
Where IDV Sits in Your Policy
Third-party liability cover is mandatory under the Motor Vehicles Act, 1988. It pays for injury, death or property damage you cause to others, so it has no IDV attached. IDV belongs to own-damage cover, which comes with a package policy or a standalone own-damage policy. If you hold only third-party insurance, damage to your own car is not covered, whatever its value.
How Insurers Work Out the Figure
The starting point is the manufacturer’s listed selling price for your make, model and variant, which already includes factory-fitted accessories. Standard private-car policy wordings then apply age-based depreciation: 5% for a car up to six months old, 15% up to one year, 20% up to two years, 30% up to three, 40% up to four and 50% up to five. Accessories fitted after purchase are added only if you declare them, and they are depreciated too.
Take a car with a listed price of ₹8 lakh that is two and a half years old. A 30% reduction gives an IDV of about ₹5.6 lakh before any declared accessories. Once a car crosses five years, or the model is discontinued, there is no fixed schedule. The IDV is then agreed between you and the insurer, usually based on the car’s condition and resale value. If you want to test different values before renewing, a guide on how IDV in car insurance is calculated also shows how moving the figure up or down shifts both your premium and your payout.
Why the Number Matters at Claim Time
Policy wordings generally treat a car as a constructive total loss when the cost of retrieval and repair goes beyond 75% of the IDV. The claim is then settled with the IDV as the upper limit, after any applicable deductible and subject to policy terms. The insurer either takes the damaged car as salvage or deducts its salvage value from the payout if you keep it.
Theft works differently in practice. Claims are usually settled only after the police issue a non-traceable report, so the payout is not immediate. For partial damage, IDV does not set the repair bill. Depreciation on parts, the compulsory deductible and exclusions decide that amount. A low IDV still hurts, though, because it lowers the 75% threshold and a badly damaged car may be written off at a figure below its resale value.
The Trade-off Between Premium and Cover
Insurers usually let you adjust IDV within a permitted range when you buy or renew. Lowering it reduces the own-damage premium, but the saving is often small compared with the cover you give up. Choosing the top of the range is not always better either. If that figure is higher than what your car would actually fetch on resale, you are paying for value you may never recover.
Your no-claim bonus is separate. It is a discount on the own-damage premium for claim-free years and has no effect on the car’s IDV. A quote that looks cheap because the IDV has been cut is not the same as one that is cheap because of a genuine discount.
What IDV Will Not Cover
The biggest gap is between IDV and what you paid on the road. Since registration and road tax are left out, a total loss on a new car can leave you short even in the first year. Return to invoice is an optional add-on that may cover this gap for eligible newer cars, at an extra premium and subject to its own conditions. Zero depreciation is a different add-on that affects how parts are paid for during repairs, not the IDV.
Undeclared accessories and CNG or LPG kits not recorded on the registration certificate and policy may not be paid for. Standard exclusions also apply, such as damage while driving under the influence, driving without a valid licence and normal wear and tear.
Smart Checks Before You Renew
Compare the IDV, not just the premium, across every quote you receive. Check that accessories added after purchase are declared and that any fuel kit is endorsed. For a car older than five years, keep service records and recent resale listings handy to support the value you ask for.
Read the policy wording and the Customer Information Sheet before paying, because depreciation rules, deductibles and add-on conditions differ between insurers and plans. A few minutes spent on the IDV figure now can make a real difference to the amount you receive after a theft or a major accident.